Brazilian REIT vs Apartment in Balneário Camboriú 2026
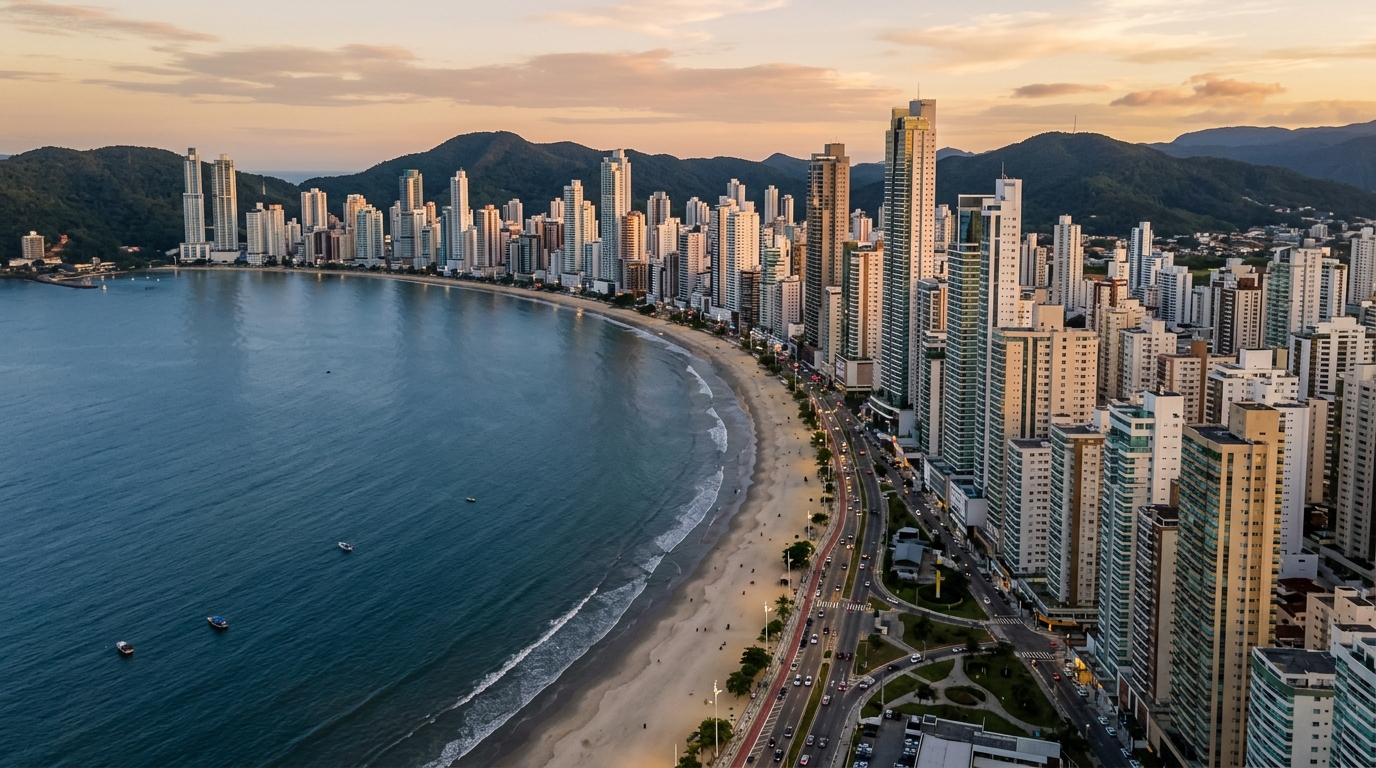
In May 2026, the price per square metre in Barra Sul, the southern beachfront strip of Balneário Camboriú, crossed R$ 22,800 (about US$ 4,300 at the current exchange rate), according to FipeZap, Brazil's leading residential price index. In the same month, the IFIX — the benchmark index for Brazilian REITs (FIIs) traded on the B3 stock exchange — closed April paying an annualised dividend yield close to 11.4%, fully exempt from personal income tax under current Brazilian rules. Meanwhile, the Selic (Brazil's base interest rate, the equivalent of the U.S. Fed funds rate) sits at 11.75%, and inflation measured by the IPCA (the official consumer price index) runs at 4.3% over the trailing twelve months. Against that backdrop, an investor sitting on R$ 500,000, R$ 800,000 or R$ 2 million — whether Brazilian or foreign — has to answer an apparently simple question: buy shares in a Brazilian REIT, or buy bricks and mortar on the most expensive coastal strip in southern Brazil?
The honest answer starts by refusing the lazy comparison between IFIX gross yield and the gross rental yield of an oceanfront apartment. The two numbers only sit on the same axis after you strip out taxes, operating costs, vacancy, sale commissions and — for physical property — capital tied up in transfer tax, deed registration, furniture and several months of grace period. This piece runs that calculation through to the end with 2026 numbers, shows the scenarios in which the REIT wins, the scenarios in which a Balneário Camboriú apartment still beats the paper, and explains why the choice is almost never binary for anyone whose investable assets sit above half a million reais.
Reframing the question: net return, horizon and investor profile
The first distortion that has to die is the "monthly income" framing. A Brazilian REIT pays distributions every month; physical property appears to pay every month through rent. The similarity hides structural differences that change the answer entirely. Comparing 0.9% per month tax-free from a REIT with 0.5% gross cap rate on a Balneário Camboriú residential apartment is comparing net paper income against gross brick income — and on any institutional desk, that is a basic error.
The correct yardstick is total net return adjusted for horizon and tax profile. "Total" includes the distribution plus share-price (or property) appreciation; "net" accounts for the 27.5% withholding income tax on residential rent for an individual landlord without a holding company structure, plus the 6% sale commission and capital gains tax when the cycle closes. Horizon changes everything: a Brazilian REIT settles in two business days and can be liquidated in a single morning; an apartment in Barra Sul can take three to twelve months to monetise during a high-rate cycle, as Secovi-SC's own absorption survey (the trade body of São Paulo and southern Brazil's real-estate brokers) has shown over the last two years.
Investor profile weighs as much as the numbers. Someone looking for stable income to top up retirement does not have the same tolerance for mark-to-market volatility as someone in the accumulation phase. Someone who plans to live in the property or use it part of the year removes vacancy from the equation, but also loses any meaningful comparison with a financial asset — they are consuming, not investing. The right question, therefore, is not "which yields more", it is "which yields more for my horizon, my tax profile and the use I expect to make of the asset".
The 2026 numbers: IFIX, cap rate, summer season and the Selic benchmark
The IFIX entered 2026 with 121 eligible funds and an average dividend yield between 10.5% and 12% per year, depending on the segment — bricks (lajes corporativas, shoppings, logistics), paper (mortgage-backed receivables) or hybrid. On a tax-free monthly basis, that translates to 0.8% to 1.0% net per month in the investor's pocket. The best logistics and granular receivables funds paid above that during 2025, but with intra-year share-price volatility above 8% — real, non-trivial risk.
The residential cap rate in Balneário Camboriú varies by district, building age and finish quality. In two- and three-bedroom apartments in Barra Sul, Centro and Vila Real, cross-referenced data from local brokerages and FipeZap put gross monthly rent at 0.35% to 0.55% of property value — before property tax (IPTU), condominium fees, vacancy and income tax. In high-end oceanfront buildings (Pioneiros, Mirante do Quebra-Mar), the cap rate drops below 0.30%, because the price per square metre already prices in heavy expectations of appreciation.
Summer-season rental changes the picture, but only for two or three months. A well-located, furnished apartment operated by a professional vacation-rental manager earns 0.7% to 1.1% of property value per month during December, January and early February — the southern hemisphere's peak season. For the rest of the year, that same apartment rarely clears 0.2% to 0.3% gross per month, and the annualised average tends to end up close to traditional residential rent — when it ends up there at all, because in some seasons heavy rain, a stronger dollar pushing Brazilian tourists toward competing destinations, or simple oversupply of short-term rentals push occupancy down. ABIH-SC (the local hotel federation) and CBIC's quarterly economic bulletin have already recorded high-season occupancy drops in years after 2023.
The benchmark that actually matters is the Selic. With the policy rate at 11.75% and the latest Focus Report — the Brazilian central bank's weekly survey of market expectations — forecasting a slow decline to somewhere between 9.75% and 10.5% by the end of 2026, Brazil's Tesouro Selic government bond pays roughly 9.3% net per year after two years, with zero credit risk and daily liquidity. That is the investor's real floor. Any risk asset that pays less than that on a risk-adjusted basis is destroying capital. The IFIX at 11% tax-free is equivalent, on a pre-tax basis comparable to taxed fixed income, to roughly 13% to 14% — well above the floor. A Balneário Camboriú apartment at a 0.30% net monthly cap rate — we'll return to that number — equals 3.6% net per year. Without appreciation, it loses badly to fixed income.
The invisible costs of bricks and mortar in Balneário Camboriú
This is where most amateur spreadsheets fall apart. Gross monthly rent of 0.5% is not what hits the owner's pocket. There is a cascade of costs that the listing agent never shows in the brochure and that the property enthusiast deliberately ignores.
It starts with the purchase. In Balneário Camboriú, ITBI — the municipal property transfer tax — runs at 3% of the official assessed value (and the city hall updated the valuation base in 2024, making transactions more expensive). Add the public deed and registry costs, which on an R$ 800,000 apartment come to between R$ 18,000 and R$ 25,000 depending on the notary. On off-plan purchases, the INCC (the construction cost index calculated by Fundação Getulio Vargas) adjusts the outstanding balance month by month — in 2025 it accumulated close to 6.4% and in 2026 is expected to finish at 5% to 6%, per projections from Sinduscon (the construction industry union) and CBIC (the national construction industry confederation). That is leveraged inflation working in the developer's favour, not yours.
Once you take possession, the monthly bleed begins. Condominium fees in a premium Balneário Camboriú tower rarely sit below R$ 2,500 per month — in towers with heated pool, spa, beach service, double garage and 24-hour concierge, they pass R$ 3,500. Property tax (IPTU) on apartments valued at R$ 1 million to R$ 1.5 million runs between R$ 6,000 and R$ 12,000 per year. Average vacancy in traditional residential rental in the city, according to Secovi-SC surveys, swings between 5% and 9% per year. If the apartment is rented out, the rental income is taxed at 27.5% under the individual progressive income tax table — no exemption, no reduced rate for individuals.
And there is the exit cost no one wants to face. The sale commission for Balneário Camboriú real-estate agents is standardised at 6% of the sale price. Capital gain above the original purchase value is taxed at 15% (with exemption only for sales below R$ 35,000 and specific reinvestment rules for primary residences). Once all of that flows through the model, the gross cap rate of 0.5% per month evaporates.
| Item | R$ 1.5M apartment in BC | R$ 1.5M in Brazilian REIT shares |
|---|---|---|
| Transfer tax / brokerage on entry | ~R$ 45,000 (3% ITBI) + deed costs | ~R$ 7,500 (0.5% average brokerage) |
| Gross monthly yield | 0.45% (R$ 6,750) | 0.92% (R$ 13,800) |
| Condominium + property tax | ~R$ 3,000/month | R$ 0 |
| Average annual vacancy | 5–9% | 0% |
| Income tax on distributions | 27.5% (individual, no holding) | 0% (current rule) |
| Exit cost | 6% commission + 15% capital gains | 0.5% brokerage + 20% on gain |
| Estimated net monthly yield | 0.28% to 0.35% | 0.82% to 0.95% |
The exercise is brutal but it is the only honest one. A gross cap rate of 0.5% in Balneário Camboriú, after property tax, condominium, 7% vacancy and 27.5% income tax, lands around 0.30% per month — under 4% per year before any appreciation. The average IFIX REIT pays nearly three times that in current income, tax-free, with two-business-day liquidity. That is the starting point of the analysis.
Where the REIT beats the apartment: liquidity, ticket size, diversification and tax
The Brazilian REIT was not invented to replace the apartment; it was invented to solve the structural problems of property as an investment vehicle. Four of those problems are unavoidable and explain why the IFIX grew from R$ 70 billion in market capitalisation in 2018 to more than R$ 240 billion in 2025.
The first is liquidity. Selling an apartment in Barra Sul in January 2026, with a high Selic and the heavy inventory that Secovi-SC reported in its latest Census, can take six to twelve months to closing. A REIT share sells in seconds on any trading session, settling in two business days. For an investor who needs flexibility — medical emergency, opportunity in another asset, relocation — that gap is priceless. For a foreign investor, who may need to repatriate capital across exchange-rate cycles, it is doubly relevant.
The second is ticket size. A decent apartment in Balneário Camboriú starts at R$ 600,000. A REIT share averages around R$ 100. An investor with R$ 800,000 can, through REITs, diversify across 12 to 20 funds in different segments — corporate floors, logistics, shopping malls, mortgage-backed receivables, agribusiness — and dozens of underlying properties. With direct real estate, the same capital buys a single apartment. Geographic, sectoral and tenant concentration, all bundled into a single postcode on the southern Brazilian coast.
The third is professional management. The REIT has a salaried manager, regulated by the CVM (Brazil's SEC), with a mandatory monthly management report and formal shareholder meetings. The individual owner in BC operates alone: negotiates with tenants, chases late rent, manages renovations, argues with the building manager. Management cost exists on both sides, but inside the REIT it is embedded in the management fee; for the property owner it is time and personal grind, rarely accounted for.
The fourth, and the most relevant today, is tax. Distributions paid by Brazilian REITs remain exempt from personal income tax, provided the shares are listed on the exchange, the fund has more than 50 holders and the investor holds less than 10% of the total. That exemption has been under political attack for at least three administrations. Bill 1,087/2025, currently in Congress, proposes a 5% rate on REIT distributions. Even if approved in current form, the REIT would still keep a tax advantage over residential rent — but the margin would tighten. A serious investor needs to track the Senate's Economic Affairs Committee in 2026 with the same attention they give to Copom, the central bank's monetary policy committee.
Where Balneário Camboriú still beats the REIT
Reducing the debate to net yield would be dishonest. There are four vectors on which bricks and mortar on the southern Brazilian coast offer something no REIT can replicate — and each one shifts the equation for the wealth-focused investor.
The first is leveraged inflation on off-plan purchases. In a typical Balneário Camboriú pre-construction launch, the buyer pays 20% to 30% down to handover and finances the rest through a developer instalment plan indexed to the INCC construction index. When the INCC runs at 6% per year and expected neighbourhood appreciation over the construction cycle (24 to 36 months) exceeds 25% — plausible in districts like Praia Brava in Itajaí and Pioneiros in BC, per FipeZap's historical base and ABRAINC (the developers' national association) reports — return on capital actually deployed can exceed 18% per year during construction. No REIT structurally achieves that kind of operating leverage without debt.
The second is historical appreciation. Balneário Camboriú led the FipeZap residential appreciation ranking among 50 Brazilian cities in three of the last five years. The average price per square metre rose from R$ 9,800 in 2019 to more than R$ 15,500 in 2025 — cumulative appreciation above 58% in the period, against cumulative IPCA inflation close to 39%. In premium districts, real appreciation (above inflation) topped 35%. No Brazilian REIT had share-price performance comparable on the same time horizon.
"The northern coast of Santa Catarina is not an ordinary real-estate market. It is a rare combination of internal migration demand from wealthier Brazilians, South American capital looking for a currency hedge, and limited oceanfront supply — and as long as that combination exists, appreciation will stay above the national average, even in a high-Selic cycle." — internal market analysis, based on the latest Secovi-SC and Sinduscon-Vale do Itajaí reports.
The third is wealth succession. Property can be donated during the owner's lifetime with usufruct retained, contributed to a family holding company, and split among heirs with clear rules. Long-term tax engineering, well executed, lowers effective inheritance tax (ITCMD, a state-level tax) and protects wealth across more than one generation. A REIT is a financial asset — it enters probate, pays inheritance tax at the full state rate (8% in Santa Catarina on the market value of the shares), and succession flexibility is narrower. For families with over R$ 5 million in net worth, that detail matters.
The fourth is personal use. Buying an apartment to spend two months a year facing the ocean is a consumption decision, not an investment decision — but it is a decision that bundles consumption, currency hedge and potential appreciation into a single asset. A REIT does not take a summer holiday. Someone seeking that combination is not solving the same problem as the investor chasing yield, and that difference has to be clear before any numerical comparison.
R$ 800,000 simulation: three scenarios out to 2031
The exercise below applies real 2026 numbers to a starting capital of R$ 800,000, across three scenarios, with a 60-month horizon (2026 to 2031). Assumptions: average Selic of 10.5% over the period (12 months at 11.75% then gradual decline), average INCC of 5.5% per year, IPCA inflation of 4.2% per year and average IFIX dividend yield of 10.8% — all three premises aligned with the May 2026 Focus Report and the most recent CBIC bulletins.
Scenario 1 — REIT portfolio with full reinvestment. R$ 800,000 distributed across a diversified portfolio of 15 IFIX REITs, with a tax-free DY of 10.8%, reinvesting every monthly distribution into new shares. Estimated terminal capital in 2031: R$ 1.32 million, ignoring share-price variation. With real share-price variation matching IPCA inflation (neutral scenario), terminal capital rises to R$ 1.62 million. Full liquidity throughout the period. Risk: mark-to-market drawdowns during high-Selic cycles — in 2025 the IFIX had an intra-year drawdown of 9%.
Scenario 2 — finished apartment in Balneário Camboriú, traditional long-term rental. R$ 800,000 apartment in an established district (Centro, Vila Real, parts of Barra Sul), minus R$ 28,000 in ITBI and deed costs. Gross monthly rent of 0.45% (R$ 3,480), after 27.5% income tax, R$ 1,100 monthly condominium fees, R$ 4,800 annual property tax and 7% average vacancy: net annual cash flow around R$ 17,000. Over 60 months, R$ 85,000 accumulated in net rental income. Property appreciation at 6.5% per year (FipeZap's recent historical average for BC) takes the asset to R$ 1.09 million in 2031. Gross total on exit: R$ 1.17 million minus 6% commission and 15% on the capital gain — R$ 1.03 million net in hand. No intermediate liquidity.
Scenario 3 — off-plan apartment in a high-appreciation district. R$ 1.1 million off-plan unit in a high-absorption region (Praia Brava, Pioneiros, Barra Norte), with 25% down (R$ 275,000) and the balance financed over 36 months through a developer instalment plan indexed to INCC. Capital actually committed during the first 36 months: roughly R$ 600,000 (down payment plus construction instalments). The remaining R$ 200,000 of starting capital parked in Tesouro Selic. At handover, estimated appreciation of 28% on original price (moderate scenario, aligned with Balneário Camboriú's track record): apartment is worth R$ 1.4 million. Rented out for the final 24 months and sold in 2031 at R$ 1.55 million (additional appreciation). Estimated 2031 total, net of costs: R$ 1.28 million. Risks: construction delay, distrato (off-plan contract cancellation), and rate-cycle changes that compress resale liquidity.
In all three scenarios, the reinvested REIT portfolio with neutral share-price variation leads. But the result is sensitive to assumptions: if the Selic surprises upward and stays above 12% throughout the period, IFIX prices fall and scenario 1 underperforms — for a Balneário Camboriú apartment, the impact on appreciation is smaller and slower. If Bill 1,087/2025 passes with full taxation, scenario 1 loses another 1 to 1.5 percentage points per year. On the other hand, if the Santa Catarina summer season collapses (climate, currency, oversupply), scenario 2 deteriorates. The simulation is not a return promise — it is a sensitivity map.
Conclusion: the thesis and the errors that destroy the result
The honest numerical answer is that, in 2026, for an individual investor with R$ 500,000 to R$ 2 million in liquid capital, the Brazilian REIT offers the best risk-adjusted net return on current income — and the margin is wide. Physical property in Balneário Camboriú only justifies itself when expected real appreciation above the historical average, leveraged inflation through INCC on off-plan purchases, well-structured wealth succession or actual personal use enter the equation. None of those advantages show up in the monthly yield table — all require long horizon and strategic reading.
Four recurring errors destroy the analysis before it even begins. The first is comparing gross yield against gross yield — the apartment loses badly once the invisible costs enter the model, and whoever ignores that is buying a 0.30% net monthly asset believing it is a 0.50% asset. The second is treating geographic concentration as a detail; having 100% of one's wealth in a single neighbourhood on the southern Brazilian coast is real risk, not diversifiable within the property itself. The third is assuming property "only goes up" — the FipeZap base shows cycles in which Balneário Camboriú spent three consecutive years below inflation. The fourth, and the subtlest, is ignoring regulatory risk: the REIT tax exemption exists today, has been narrowed in the past and may be revised again. Anyone betting everything on that vehicle has to monitor the CVM, the Senate and the Receita Federal (Brazil's IRS) with the same seriousness with which they monitor the Selic.
The sophisticated investor in 2026 does not choose between REIT and apartment. They structure an allocation that combines both — using the REIT for monthly income, liquidity and sectoral diversification, and using the Balneário Camboriú apartment for wealth leverage, oceanfront appreciation and a succession vehicle. The right question was never "which yields more", it was "what role does each one play in the portfolio". SIDE Empreendimentos tracks the launch cycle of the northern Santa Catarina coast closely and, through its analysis channel, publishes weekly reports that cross-read cap rate, INCC and macro indicators — investors who want to keep the radar calibrated can subscribe to the free analysis and receive the next update in their inbox.