Foreign Property Taxation in Brazil 2026: SC Coast Guide
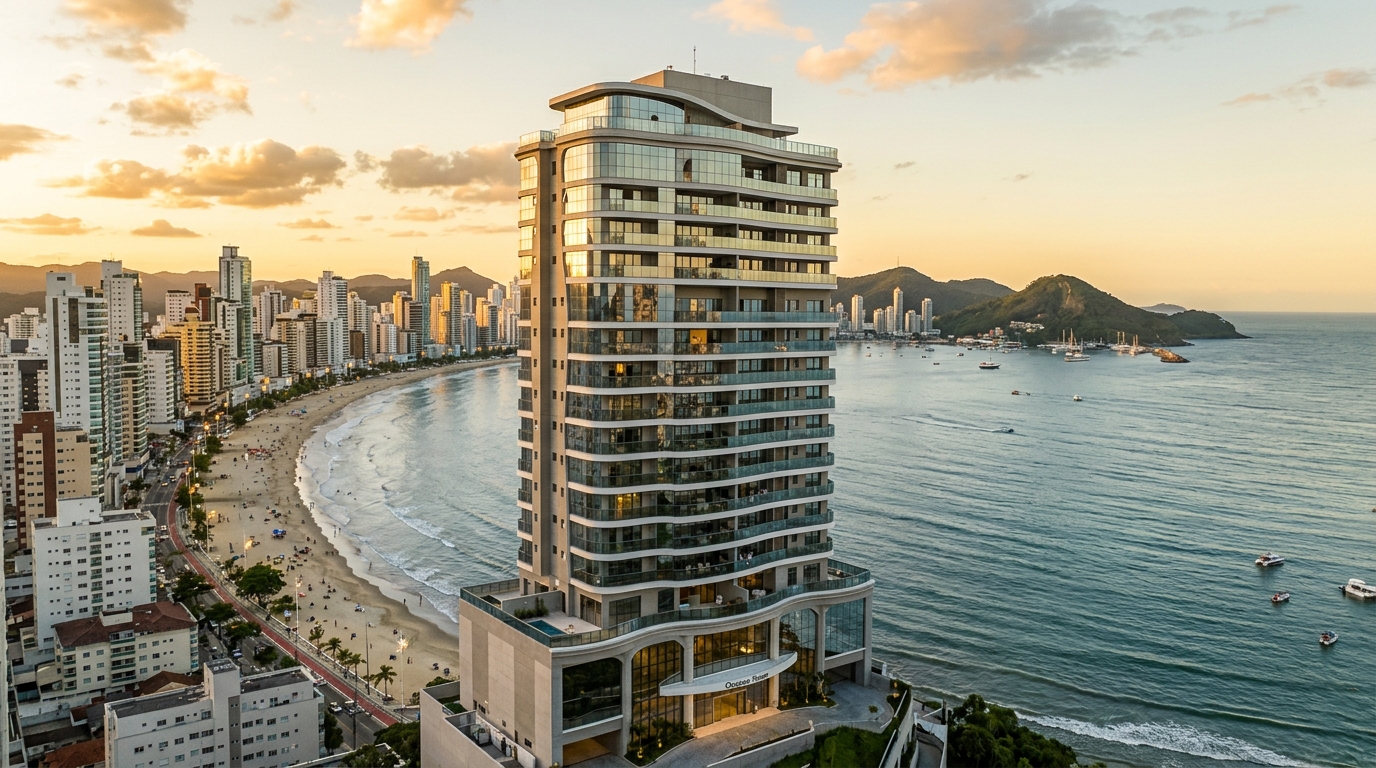
A Portuguese investor who bought a pre-construction apartment in Balneário Camboriú in 2021 for R$ 2.8 million and sold it in May 2026 for R$ 4.1 million discovered, at the moment of remitting the euro proceeds home, that his taxable capital gain in Brazil was not R$ 1.3 million — it was R$ 1.9 million. The difference did not come from Receita Federal (Brazil's federal tax authority) tightening the rules. It came from the way Normative Instruction RFB 208/2002 forces the calculation to be performed in Brazilian reais, ignoring the cumulative currency depreciation between purchase and sale. Applied to that base, the progressive rates established by Law 13.259/2016 — withheld through the tax liability imposed on the Brazilian buyer — consumed roughly R$ 295,000 before the money ever left Sisbacen, the Central Bank's foreign-exchange registration system.
The example is typical of what is now seen in the high-end of Itajaí, Praia Brava and Itapema, ever since the AMFRI coastal corridor in Santa Catarina became a preferred destination for Iberian and Argentine family offices. Those who enter Brazil without grasping the tax architecture surrender returns at the exit. Those who enter with the correct structure — CPF (the Brazilian individual taxpayer ID) obtained on time, RDE-IED foreign direct investment registration filed with Sisbacen, an operational non-resident bank account and a deliberate choice between individual ownership and a real-estate holding company — preserve the currency spread and protect the estate. This guide consolidates the 2026 fiscal framework for the non-resident considering the purchase, lease or sale of premium residential property on the Santa Catarina coast.
The 2026 backdrop: who counts as a "non-resident taxpayer" and why the SC coast hit the radar
Brazil entered 2026 with the Selic (the country's base interest rate) on a gradual easing path after the 2024-2025 peak, and the real is trading in a band that still favours external capital denominated in euros or dollars. That foreign-exchange tailwind, combined with one of the highest concentrations of high-end residential VGV (Valor Geral de Vendas, the aggregate sales value of new launches) per square kilometre in the country — industry data from ABRAINC and CBIC, the leading Brazilian developer associations, show that the northern coast of Santa Catarina accounted for a disproportionate slice of national premium launches in 2024-2025 — has turned Balneário Camboriú, Itajaí and Itapema into anchor markets for qualified foreign investors.
Before any transaction, however, one must pin down the definition that drives the entire tax treatment. For Receita Federal, a "non-resident taxpayer" is an individual who has left Brazil on a permanent basis, who has spent more than twelve months outside the country on a temporary basis without filing the Communication of Definitive Departure, or who has never been a Brazilian resident. A foreigner holding a permanent visa and actually living in Brazil is a tax resident and is taxed exactly like any local citizen. The non-resident status therefore requires an individual title-holder based abroad, formally identified by a CPF and by a country of fiscal residence — and it is this status that triggers the specific rules on withholding, remittance and capital gains discussed in the sections that follow.
The status of the country of origin matters just as much. Normative Instruction RFB 1,037, periodically updated, lists jurisdictions classified as tax havens or privileged tax regimes. Investors domiciled in those jurisdictions face penalty rates — 25% on rental income, for instance, against the standard 15% — and lose access to deductions and to some of the progressive brackets that apply to capital gains. Checking the list in force before deciding on the acquisition vehicle is one of the first steps of due diligence, especially for buyers who route ownership through Caribbean or Channel Islands structures by reflex.
Pre-acquisition: CPF, RDE-IED at Sisbacen and the non-resident bank account
No deed is recorded at a Brazilian notary office without the buyer's CPF. For the non-resident, the document is issued through Banco do Brasil, Itaú, a Brazilian consulate abroad or directly through a fiscal representative in Brazil acting under power of attorney. The supporting document showing country of fiscal residence must be consistent with what will later be declared in the systems of the federal tax authority and the Central Bank. Inconsistencies between the CPF registration and the foreign investment record are one of the largest sources of remittance blockage at the moment of sale, often surfacing only when the seller tries to convert the proceeds back into euros or dollars.
The second step, frequently skipped in transactions below R$ 5 million, is the RDE-IED — Registro Declaratório Eletrônico de Investimento Estrangeiro Direto, the Central Bank's electronic foreign direct investment registry, currently governed by BCB Resolution 277/2022 and operated within Sisbacen. Every inflow of external capital intended for the purchase of property by a non-resident individual, or for capital contribution into a Brazilian company that will hold the property, must be registered. The RDE-IED is what legitimises the future remittance of principal and income. There is no outbound foreign-exchange operation without a corresponding registered inflow — and attempts to regularise the registration after the fact, with the sale already negotiated, typically cost months of paralysis and meaningful foreign-exchange advisory fees.
The non-resident bank account, known as CNR and currently governed by the consolidated Central Bank regulation that succeeded the former Resolution 4,373, is the third pillar. It allows the foreign owner to receive rent in reais, pay local taxes, fund renovation work and condominium fees and, at the right moment, convert balances into foreign currency without queueing behind ordinary personal remittances. A power of attorney executed at a Brazilian consulate abroad, or in Brazil with proper notarisation, completes the operational set-up: the local attorney-in-fact — typically a tax lawyer or a family office with a fiscal arm — assumes responsibility for ancillary obligations and for the rental income withholding discussed later in this guide.
Acquisition: ITBI, deed, laudêmio on shoreline land and the holding-company option
The Imposto sobre Transmissão de Bens Imóveis (ITBI), Brazil's municipal real-estate transfer tax, is due upon recording of the deed, and the rate ranges between 2% and 3% in the Santa Catarina municipalities that concentrate the premium inventory. The technical milestone that matters for the high-ticket investor is Theme 1,113 of the Superior Court of Justice (STJ), decided in 2022 with binding effect: the ITBI base is the actual transaction value declared by the parties, with a presumption of accuracy that the municipality can only rebut through a formal administrative proceeding. The earlier practice, in which city halls arbitrarily set a "reference market value" above the price stated in the deed, has lost legal footing. Deals of R$ 4 million or more along the Itajaí-Itapema corridor are now routinely shielded by an independent appraisal report, precisely to underpin the declared base and prevent a later assessment.
| Municipality | ITBI rate 2026 | Calculation base | Notes |
|---|---|---|---|
| Itajaí | 2% | Transaction value (STJ Theme 1,113) | Port area and Praia Brava under tight documentary scrutiny |
| Balneário Camboriú | 2% | Transaction value | Heavy concentration of units above R$ 5 m; reinforced title due diligence |
| Itapema | 2% | Transaction value | Meia Praia strip expanding aggressively in VGV |
| Camboriú (mainland) | 2% | Transaction value | Smaller ticket sizes; zoning verification advised |
Properties sitting on terreno de marinha — federal shoreline land, a common situation along stretches of the Santa Catarina coast and especially on the older lots — add the laudêmio payable to the Secretariat of Federal Patrimony, fixed at 5% of the value of any onerous transfer, plus an annual occupancy or land-tenure fee. The foreign investor must identify the land-tenure nature of the lot in the property registry before signing the price, or risk understating the all-in acquisition cost by as much as five full percentage points on the headline value.
When the acquisition is structured through a Brazilian real-estate holding company — a limited liability entity (sociedade limitada) set up to receive the property as a capital contribution from the foreign shareholder — Theme 796 of the Supreme Federal Court (STF) comes into play. In ruling on Extraordinary Appeal 796,376, the Supreme Court restricted the constitutional immunity provided in Article 156, §2, item I of the Constitution: the capital contribution is immune from ITBI, but only up to the limit of the subscribed corporate capital; any portion of the property's market value that exceeds the capital actually paid in is taxed normally. For the structure to be efficient, the share capital must reflect the economic value of the asset contributed, and the corporate documentation must sustain that equivalence in the event of municipal scrutiny.
Holding the asset: income tax on rent, IPTU and the individual-versus-holding comparison
Once the acquisition is settled, the holding phase — short-term rental, annual lease or a mix — defines the recurring fiscal drag. For the non-resident individual, rent paid by a Brazilian tenant is subject to a 15% flat withholding on the gross amount, paid by the local attorney-in-fact via a DARF (the federal tax payment slip) with the proper revenue code, and reported annually through the DIRF return. For holders domiciled in jurisdictions listed in IN RFB 1,037, the rate rises to 25%, and any chance of crediting that tax against the bill in the country of origin depends on the existence of a bilateral treaty.
The IPTU, Brazil's municipal annual property tax, is a deductible expense when the structure runs through a holding company, but it is not deductible under the withholding regime that applies to the non-resident individual. In Balneário Camboriú and Itajaí, both the rates and the assessed values have been revised in recent cycles and now materially affect the effective cap rate on units above R$ 6 million. This is one of the recurring triggers for migrating to a holding structure once a portfolio crosses four units.
A real-estate holding company under the lucro presumido regime — Brazil's deemed-profit corporate income tax framework — applies a 32% presumed margin on gross rental revenue for IRPJ (corporate income tax) and CSLL (social contribution on net profit), plus the cumulative PIS and Cofins social contributions. The combined effective load on gross rental revenue typically lands around 14.53%, against the 15% withholding faced by the non-resident individual — and against 25% if the holder sits in a tax-haven jurisdiction. The apparent advantage of the holding structure, however, must absorb the running cost of corporate maintenance, bookkeeping, the eventual ITCMD inheritance and gift tax on quotas at succession, and the operational complexity of remitting dividends to the foreign shareholder. The seasoned investor's mental shortcut is straightforward: up to two units, individual ownership usually wins; from three or four premium units onward, or in any arrangement involving estate planning, the holding company tends to dominate.
"The most expensive mistake a foreign investor makes in Brazil is not the rate — it is the structure. Those who enter as individuals believing they are saving on professional fees later discover, at the sale or at the inventory proceeding, that they paid twice over what a well-designed holding company would have cost from day one." — a recurring observation in the tax-advisory circles operating along the Itajaí-Florianópolis corridor.
The exit: progressive capital gains tax, buyer-side withholding and treaty relief
The sale is the moment of truth. For the non-resident, the capital gain is governed by Law 13,259/2016, which introduced progressive rates: 15% on the gain up to R$ 5 million, 17.5% on the bracket between R$ 5 million and R$ 10 million, 20% between R$ 10 million and R$ 30 million, and 22.5% above R$ 30 million. Unlike a Brazilian-resident individual, the non-resident has no access to the exemptions and gain-reduction factors of Law 7,713/1988 — there is no "reduction factor" for holding period, and no exemption for reinvesting the proceeds in another residential property.
The technical point that destroys investment theses is the calculation in reais. IN RFB 208/2002 mandates that both acquisition cost and sale value be considered in nominal reais, with no adjustment for currency movement. This means that, in windows of real depreciation, the gain expressed in hard currency may be far smaller — or even negative — than the gain taxable in reais. The case at the opening of this guide is precisely that: the Portuguese investor bought at around R$ 5.20 per euro and sold at around R$ 6.10 per euro, and the federal tax authority simply ignored the currency spread in the assessment. Foreign buyers used to the German or Spanish models, where the cost base is restated in the home currency, are routinely caught off guard.
Responsibility for paying the tax, in a transaction with a non-resident seller, falls on the Brazilian buyer or on the seller's Brazilian attorney-in-fact, under IN RFB 208/2002. In practice, the notary will not record the deed without proof of the DARF payment, which turns the negotiation delicate when buyer and seller have not previously agreed on who carries the financial burden of the tax at closing. The "net-to-seller" clause is now a standard contractual provision in transactions involving foreigners along the AMFRI corridor, and overlooking it routinely costs days of rework at the closing table.
Double-tax treaties soften the final bill for the European investor. Brazil and Portugal have maintained the Convention to Avoid Double Taxation in force since the early 2000s, and the same applies to Spain. With the United States, however, no treaty is in force, and the American investor who pays the gain in Brazil must rely on the Foreign Tax Credit on the IRS return, with the limitations that mechanism entails. Argentines, the second most common nationality in the Balneário Camboriú high-end after Europeans, operate under a bilateral treaty signed decades ago, with property-specific nuances that warrant case-by-case review.
Remittance, corporate structures, succession and the mistakes that destroy the thesis
Once the tax is assessed and paid, the remittance of the sale proceeds runs through a Brazilian bank authorised to deal in foreign exchange, backed by the RDE-IED registration of the original inflow. The IOF-Câmbio, Brazil's tax on foreign-exchange operations applied to capital repatriation, is on a declining schedule that points toward zero by 2028, but the rate in force on the operation date must be checked case by case. The required documentation includes the proof of capital-gains tax payment, the foreign-exchange contract, the recorded deed and the RDE-IED itself with the write-down of the investment.
The foreign investor with Brazilian assets above the thresholds set by the Central Bank also has reporting duties on the reverse side: while the DCBE (Declaration of Brazilian Capital Held Abroad) is owed by Brazilian residents who own assets overseas, the non-resident's central obligation is filing with their own home-country tax authority and keeping the Sisbacen records up to date. Law 14,754/2023, which reshaped the taxation of offshore vehicles controlled by Brazilian residents, does not directly reach the non-resident, but it has reorganised the planning market and narrowed the use of hybrid structures — Brazilian-resident investors who held offshore vehicles to acquire property inside Brazil itself had to reconsider the whole equation.
At the estate-planning level, Santa Catarina levies the ITCMD inheritance and gift tax at progressive rates that reach 8% on transfers upon death and on lifetime gifts, under current state legislation. An R$ 8 million apartment in Praia Brava held directly by an individual can generate a liability of half a million reais in the probate proceeding, payable locally and within statutory deadlines, with little practical possibility of fast remittance by the heirs. Contributing the property to a Brazilian holding company, or to a structure that combines a domestic holding with a family vehicle abroad — when properly designed and old enough to withstand scrutiny — typically reduces the succession cost materially and, more importantly, gives the estate the liquidity it needs without forcing a distressed sale.
The five most expensive mistakes seen in advising foreign families with portfolios in Itajaí, Balneário Camboriú and Itapema keep repeating: failing to register the capital inflow at the RDE-IED on the grounds that "it is only one apartment"; ignoring the tax-haven list of IN RFB 1,037 when choosing the holder's domicile; signing a private off-record contract (contrato de gaveta) in the belief of saving notary time, only to generate a chain-of-title defect that resurfaces at the sale; understating the laudêmio on shoreline land when pricing the full ticket; and skipping ancillary filings with Receita and the Central Bank, building a silent liability that only surfaces at remittance. Each of these mistakes erodes returns by the equivalent of one or two percentage points per year over the life of the portfolio. Premium residential towers along the AMFRI corridor — among them developments delivered by consolidated local builders such as SIDE Empreendimentos in Itajaí and the surrounding region — typically offer documentary support that lowers the risk of error at the notary stage, but the buyer's tax structure remains the buyer's responsibility from end to end.
Conclusion
The Brazil of 2026 offers the foreign investor a complex but fully mapped fiscal equation: the right combination of CPF, RDE-IED, non-resident account, vehicle choice — individual or holding company —, a deed underpinned by STJ Theme 1,113 and an estate plan tuned to the ITCMD of Santa Catarina can preserve most of the hard-currency return even through adverse currency windows. The wrong combination, by contrast, hands a disproportionate share of the gain to the tax authority and to the Brazilian counterparty at closing. For the weekly analysis of taxation, foreign exchange and the residential market along the Santa Catarina coast, subscribe to the SIDE newsletter and keep the fiscal framework current before the next closing.